 Send us an e-mail






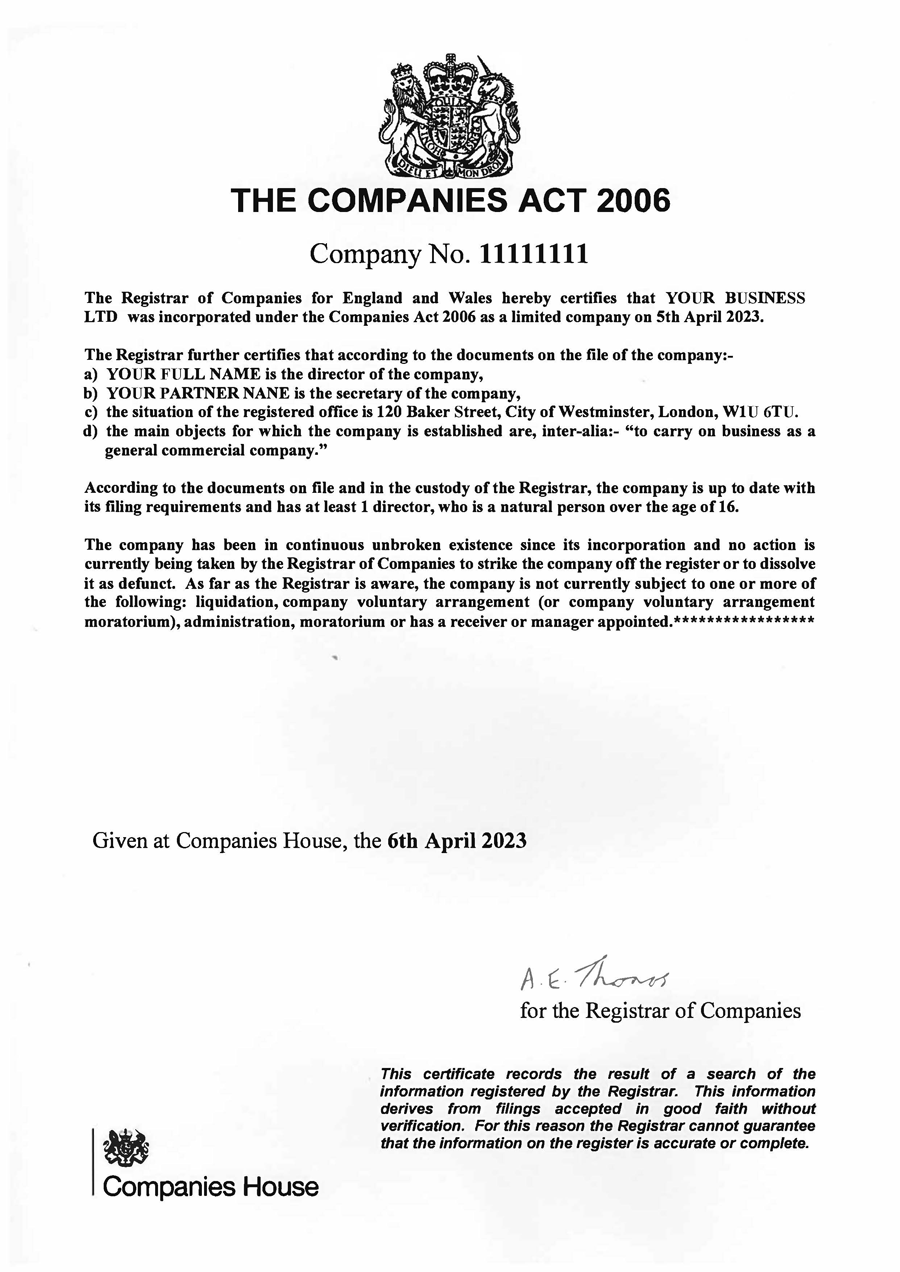


The genuine-business test
At least two persons must associate to carry on a lawful business with a view to profit. A registered address, tax aspiration or “UK subsidiary” label does not establish that business.













 9.30 am – 6.00 pm GMT
 Monday-Friday
 info@coddan.co.uk








£189.00+VATLLPStartup Essential™ Recommended for 1
package
Buy Now LLP Registration – LLP as a UK Group Operating Entity for £89 + VAT. The fixed £89 + VAT price is Coddan’s professional fee for the scope stated above and VAT is added to that fee. Companies House fees are separate: £100 standard software, £156 same-day or £124 paper; paper also requires separately agreed Coddan work. The price assumes two straightforward UK individual members; each additional UK individual is £35 + VAT, each accepted UK body-corporate member is £125 + VAT, and later admissions are separate. It is a formation base only where group assessment confirms eligibility; otherwise Coddan quotes. This is a one-off service with no automatic renewal. Incorporation does not establish a parent-subsidiary relationship, prove control, create UK substance or implement the group’s contracts, employment, funding or banking arrangements. Need initial records? Compare Registration & Initial Records. Review the full formation terms and compare LLP and company structures. Begin with international LLP formation. All four packages require prior group assessment. Overseas, mixed-member, layered-control and foreign-corporate cases ordinarily proceed through the international and complex formation route and written quotation. Companies House—not Coddan—decides whether the incorporation or later filing is accepted. |
£249.00+VATLLP Startup Records™ Recommended for 2
package
Buy Now Registration & Initial Records – LLP as a UK Group Operating Entity for £149 + VAT. The fixed £149 + VAT price is Coddan’s professional fee for the scope stated above and VAT is added to that fee. Companies House fees are separate: £100 standard software, £156 same-day or £124 paper; paper also requires separately agreed Coddan work. The price assumes two straightforward UK individual members; each additional UK individual is £35 + VAT, each accepted UK body-corporate member is £125 + VAT, and later admissions are separate. It is a formation base only where group assessment confirms eligibility; otherwise Coddan quotes. This is a one-off service with no automatic renewal. Incorporation does not establish a parent-subsidiary relationship, prove control, create UK substance or implement the group’s contracts, employment, funding or banking arrangements. Need formation only? Compare LLP Registration. Need governance? Compare Governance Setup. Review the full formation terms and see later member and PSC changes. Begin with international LLP formation. All four packages require prior group assessment. Overseas, mixed-member, layered-control and foreign-corporate cases ordinarily proceed through the international and complex formation route and written quotation. Companies House—not Coddan—decides whether the incorporation or later filing is accepted. |
£379.00+VATLLP Governance Essential™ Recommended for 3
package
Buy Now Governance Setup – LLP as a UK Group Operating Entity for £279 + VAT. The fixed £279 + VAT price is Coddan’s professional fee for the scope stated above and VAT is added to that fee. Companies House fees are separate: £100 standard software, £156 same-day or £124 paper; paper also requires separately agreed Coddan work. The price assumes two straightforward UK individual members; each additional UK individual is £35 + VAT, each accepted UK body-corporate member is £125 + VAT, and later admissions are separate. It is a formation base only where group assessment confirms eligibility; otherwise Coddan quotes. This is a one-off service with no automatic renewal. Intercompany services, funding, intellectual-property, employment, transfer-pricing and other group documents are not included. Need no agreement? Compare Registration & Initial Records. Need first-year support? Compare First-Year Administration. Review the full formation terms and read about LLP governance. Begin with international LLP formation. All four packages require prior group assessment. Overseas, mixed-member, layered-control and foreign-corporate cases ordinarily proceed through the international and complex formation route and written quotation. Companies House—not Coddan—decides whether the incorporation or later filing is accepted. |
£549.00+VATLLP First-Year Essential™ Recommended for 4
package
Buy Now First-Year Administration – LLP as a UK Group Operating Entity for £449 + VAT. The fixed £449 + VAT price is Coddan’s professional fee for the scope stated above and VAT is added to that fee. Companies House fees are separate: £100 standard software, £156 same-day or £124 paper; paper also requires separately agreed Coddan work. The £50 digital confirmation-statement fee is separate. The price assumes two straightforward UK individual members; each additional UK individual is £35 + VAT, each accepted UK body-corporate member is £125 + VAT, and later admissions are separate. It is a formation base only where group assessment confirms eligibility; otherwise Coddan quotes. The scope ends with the first confirmation statement; later administration requires affirmative renewal. Tax residence, permanent establishment, treaty, withholding, transfer-pricing, consolidation, accounting and foreign-law conclusions remain separate. Need no first-year support? Compare Governance Setup. Review the full formation terms and review LLP accounts and continuing compliance. Begin with international LLP formation. All four packages require prior group assessment. Overseas, mixed-member, layered-control and foreign-corporate cases ordinarily proceed through the international and complex formation route and written quotation. Companies House—not Coddan—decides whether the incorporation or later filing is accepted. |
Phase 2 · Restricted group-structure route · Classification C
A UK LLP can carry on a real operating business within a wider group. It has members—not shareholders or issued share capital—and incorporation does not establish a share-subsidiary relationship, UK substance, tax treatment or foreign recognition.
This page is for a UK or international group considering an LLP to provide services, trade, employ people, contract, distribute products, exploit rights or perform another defined UK operating function. A group description is not enough. The business, participants, control, evidence and implementation route must be established.
At least two persons must associate to carry on a lawful business with a view to profit. A registered address, tax aspiration or “UK subsidiary” label does not establish that business.
The UK function is real; members and control are transparent; capacity and authority are evidenced; and legal, accounting, tax, regulatory, documentary and banking dependencies are cleared or separately scoped.
The required result depends on shares, conventional equity investment, automatic group relief, uncertain foreign recognition, opaque control, unresolved capacity, missing clearance or no genuine two-person profit-seeking business.
| Candidate | Form | Possible strength | Principal dependency | Route owner |
|---|---|---|---|---|
| UK LLP | Body corporate with members | Flexible internal governance/economics | Control, accounting, tax and foreign recognition | P2-02 / A05 |
| Limited company | Share capital and shareholders | Conventional share-subsidiary model | Company, tax and investment design | A03 / professional review |
| UK establishment or branch | Part of overseas entity | No separate UK incorporated vehicle | Overseas-company and PE treatment | Professional route |
| Contractual arrangement | No new entity | Defined cooperation only | Contract, liability and tax | Solicitor/advisers |
| Holding-only vehicle | Owns assets or interests | Ownership function | Genuine-business and transfer boundary | P2-01 placeholder |
| Joint venture | Independent participants | Shared project or venture | Governance, assets and exit | P2-03 placeholder |
A03 explains the complete LLP-versus-company comparison. P2-02 applies only the group-operating boundary.
An LLP does not issue shares. A corporate member holds a membership interest, not shares in the LLP. Capital contribution, profit share, voting power, beneficial ownership and PSC status must each be established from the applicable facts and documents.
| Feature | LLP | Company | Evidence needed |
|---|---|---|---|
| Participant status | Member | Shareholder/member | Formation, admission and constitutional records |
| Capital | Contribution/capital account; no issued shares | Issued share capital where applicable | Contribution or allotment records |
| Economic return | Profit/loss allocation and drawings | Dividend/other rights | Agreement and accounting records |
| Control | Agreement, voting, appointment or actual influence | Shares, votes, appointment or other rights | Complete control evidence |
| PSC position | Separate statutory assessment | Separate statutory assessment | Rights and significant-influence evidence |
Company-law concepts of an undertaking, parent undertaking and subsidiary undertaking can depend on voting, appointment, dominant-influence or unified-management facts. Incorporation does not prove that relationship, and P2-02 never describes the LLP automatically as a share subsidiary.
A dated chart must reach through every intermediate entity to natural-person ultimate beneficial owners. It must show economic interests, voting and appointment rights, vetoes, trusts, nominees and other control. The chart supports review; it is not itself a PSC, sanctions or foreign-law conclusion.
| Layer | Jurisdiction | Legal interest | Control rights | Evidence/status |
|---|---|---|---|---|
| Proposed LLP | UK jurisdiction | Membership structure | Agreement and actual arrangements | Proposed facts |
| Direct member | Each member’s jurisdiction | Membership/economic rights | Votes, appointments and vetoes | Registry/identity evidence |
| Intermediate entity | Every layer | Shares/interests | Direct and indirect control | Registry/constitution |
| Natural-person UBO | Residence/nationality evidence | Ultimate economic interest | Ultimate or actual control | Identity/source evidence |
| Trustee, nominee or other controller | Relevant jurisdiction | Legal/beneficial distinction | Rights or significant influence | Instrument and professional review |
LLP membership, designated-member duties, internal authority, beneficial ownership, control and PSC status are distinct. Identity verification confirms identity only. Companies House implementation for LLP roles is staged, so the filing-date requirement and personal-code route must be checked at acceptance. A06 complete role explanation — controlled non-clicking placeholder.
Identify services or goods, markets, customers, suppliers, contracts, management, staff, premises, systems, licences, assets, IP, funding and banking. Incorporation or a UK registered office does not alone create substantive activity, tax residence, management and control or a permanent establishment.
| Function | Activity/evidence | Required resources | Key boundary |
|---|---|---|---|
| Services | Scope, clients, contracts and revenue | People, competence, systems | Regulatory and PE review |
| Trading/distribution | Products, suppliers, customers and risk | Stock, logistics, contracts | VAT/customs/product rules |
| Employment/service centre | Functions, supervision and cost | Staff, premises, payroll | Employment/immigration/PAYE |
| Intellectual-property (IP) exploitation | Rights, licences and income | Title and instruments | P2-11/IP professional ownership |
| Nominal or unclear function | Label without coherent operations | Insufficient | Evidence request, redirection or refusal |
Existing contracts do not transfer on incorporation. New agreements, assignments, novations or consents are separate legal work.
Formation does not transfer employees or determine employment, immigration, PAYE, secondment or worker status.
Settle capital, loans, assets, services, profit/loss shares and authority. A description does not transfer title or settle tax.
Intercompany services, funding, guarantees, security, IP, employment, transfer pricing, VAT, tax residence, permanent establishment, treaty access, consolidation, foreign recognition and banking remain separate decisions and workstreams.
| Question | Does incorporation decide it? | Required review | Owner |
|---|---|---|---|
| Residence, PE or treaty | No | Facts, jurisdictions and current law | International-tax professional |
| Transfer pricing | No | Related transactions, arm’s-length analysis and records | Tax/transfer-pricing professional |
| Member tax, VAT or withholding | No | Participants, flows and registrations | Tax/accounting professional |
| Consolidation/group reporting | No | Control and accounting framework | Accounting/audit professional |
| Foreign capacity/recognition | No | Local law and evidence | Foreign/corporate lawyer |
| Banking/regulatory acceptance | No | Independent onboarding/permission | Bank/provider/regulator |
| Evidence | Purpose | Possible route | Decision owner |
|---|---|---|---|
| Registry extract/constitution | Existence, status and powers | Current official record; translation/certification if required | A05 / foreign counsel |
| Resolution/incumbency/power | Decision and signing authority | Certification/notarisation/legalisation if destination requires | Corporate lawyer/documentary route |
| UBO and identity/address evidence | Ownership, control and KYC | Accepted identity/document route | Coddan acceptance/official decision owner |
| Foreign-law opinion | Capacity, authority or recognition | Separately instructed professional | Qualified foreign counsel |
KYC, AML and sanctions review can require evidence beyond a registry name. Opaque or inconsistent ownership, absent authority, unacceptable risk or missing professional clearance can cause a focused HOLD, referral or refusal. P2-02 does not give sanctions clearance.
Unless an agreement provides otherwise, statutory defaults include equal capital and profit shares, every member’s management right, no management remuneration, unanimous consent for a new member or voluntary assignment, majority decisions on ordinary matters, unanimity to change the nature of the business, and no expulsion without an express power.
A07 bespoke LLP agreement and governance — controlled non-clicking placeholder. A standard A04 agreement can record only settled internal governance after A05/accepted assessment. It cannot create intercompany, funding, IP, employment, tax, transfer-pricing, foreign-law, banking or regulatory documents.
| Issue | Standard scope may fit | Separate/bespoke trigger | Owner |
|---|---|---|---|
| Internal governance | Facts and decisions settled | Negotiation, dispute or unusual control | A07/solicitor |
| Contributions/economics | Clear record only | Transfer, valuation or tax issue | Legal/tax/valuation professional |
| Group control | Approved ordinary clauses fit | Bespoke veto, enforcement or parent rights | A07/solicitor |
| Operational documents | Never included | Intercompany, funding, IP, employment or transfer | Appropriate professional |
Provide the complete group chart, registry and constitutional evidence, authorities, signatories, PSC analysis, identity/address information, UK operating plan and known professional conclusions. Coddan then defines the formation scope and separately owned dependencies. No general Phase 2 assessment product, name, price, credit or checkout route is created.
| Matter | P2-02 role | Decision owner | Not included in formation |
|---|---|---|---|
| Formation | Suitability/readiness and A05 gateway | A05; later A04 if accepted | Professional conclusions |
| Capacity/foreign law | Recognise evidence dependency | Corporate/foreign lawyer | Opinion and foreign documents |
| Tax/transfer pricing | Preserve boundary | International-tax professional | Analysis, policy and filings |
| Accounting/consolidation | Preserve boundary | Accountant/auditor | Classification and group reporting |
| Contracts/IP/employment | Identify dependencies | Solicitor/specialist | Instruments and implementation |
| Banking/regulation/sanctions | Evidence and acceptance gate | Provider/regulator/professional | Approval or clearance guarantee |
A05 assessment and written-quotation destination — controlled non-clicking placeholder
Commercial route · secondary to suitability
A05 owns overseas members, corporate participants, international chains, foreign evidence and complex international formation. Only after A05 or accepted assessment confirms eligibility may an A04 level become the base for an accepted formation. A04 remains the sole package owner.
| Stage/level | Controlled role | Price reference | Availability on P2-02 | Gate |
|---|---|---|---|---|
| A05 assessment | Evidence and international/corporate route | Written quotation only | Required first | Evidence, clearance and acceptance |
| A04-L1 — LLP Registration | Accepted filing | £89 + VAT | Not directly offered | Accepted later base only |
| A04-L2 — Registration & Initial Records | Accepted filing and records | £149 + VAT | Not directly offered | Accepted later base only |
| A04-L3 — Governance Setup | Settled standard governance | £279 + VAT | Not directly offered | Questionnaire, 15-condition PASS and human review |
| A04-L4 — First-Year Administration | Defined accepted first-year scope | £449 + VAT | Not directly offered | Same fit and acceptance gate |
| Professional implementation | Tax, legal, accounting, foreign and operational work | Separate quotation/provider | Never included by implication | Relevant professional decision |
Controlled two-person assumption. Supplements: £35 + VAT for an additional straightforward UK individual member and £125 + VAT for an accepted UK body-corporate member.
VAT and Companies House fees are separate. Current official reference fees: £100 digital/software incorporation; £156 same-day software incorporation where available; £124 paper incorporation; and £50 digital confirmation statement. Identity, address, foreign evidence, documentary and professional costs are separate.
L4 has a defined first-year scope. Any later renewal requires affirmative acceptance; there is no automatic or indefinite renewal.
A05 — international and non-UK LLP formation gateway · A04 — UK LLP formation and package owner
The certificate creates the LLP. It does not implement the group’s authority, services, funding, IP, people, tax, accounting, banking, data, insurance or regulatory systems.
| Workstream | Incorporation outcome | Further action | Owner |
|---|---|---|---|
| Governance/registers | Registered LLP and filed roles | Authorities, records and accepted agreement | A04/A07 as scoped |
| Intercompany services | None | Scope, pricing, liability and records | Solicitor/tax/accounting |
| Funding/security | None | Capital, loans, guarantees and security documents | Legal/lender/tax |
| IP/contracts | No transfer or licence | Assignments, licences, novations and consents | IP/corporate solicitor |
| People/payroll | No employee transfer | Employment, immigration, payroll and secondment | Employment/tax professionals |
| Tax/accounting | No tax conclusion | Registrations, policies, accounts and group reporting | Accountant/tax adviser |
| Banking/regulatory/data | No approval | Onboarding, permissions, systems and insurance | Provider/regulator/specialist |
Continue to maintain accurate member, designated-member, PSC, ownership/control, registered-office, accounting and filing records. A09 — LLP annual accounts and A10 — LLP confirmation statements retain their complete subjects.
Assessment, formation, VAT, official fees, supplements, professional work, first-year scope and later renewal remain visibly separate.
The accepted outcome identifies the LLP, participants, filings, included records and every implementation dependency still outstanding.
Each professional conclusion stays with its owner through formation, implementation and later ownership or activity changes.
A dated chart, authority schedule, dependency register and implementation checklist reduce repetition without manufacturing conclusions.
Clear boundaries, verified links, current sources, controlled pricing and recorded decisions demonstrate the work without promotional claims.
A focused evidence request; a defined professional referral; a proposition-specific HOLD; an accepted A05 route and written quotation; redirection to a company, branch or another structure; or refusal. No outcome guarantees registration, tax treatment, foreign recognition, banking or regulatory acceptance.
Confirmed live: A03, A04, A05, A09 and A10. Non-clicking placeholders: A06, A07, A08; P2-01, P2-03, P2-13 and every other Phase 2 page; A05 assessment/application; A04 ordering/application; written quotation; and tax, accounting, transfer-pricing, foreign-law, documentary, banking, sanctions, regulatory and legal professional destinations.
P2-02 owner URL remains on HOLD
No P2-09 page, URL or destination exists. No application form, checkout, client portal, redirect or live-site alteration has been created by this production file.


Coddan CPM LTD™ Business One-Stop Shop since 2005 Doing Business Made Easier!
